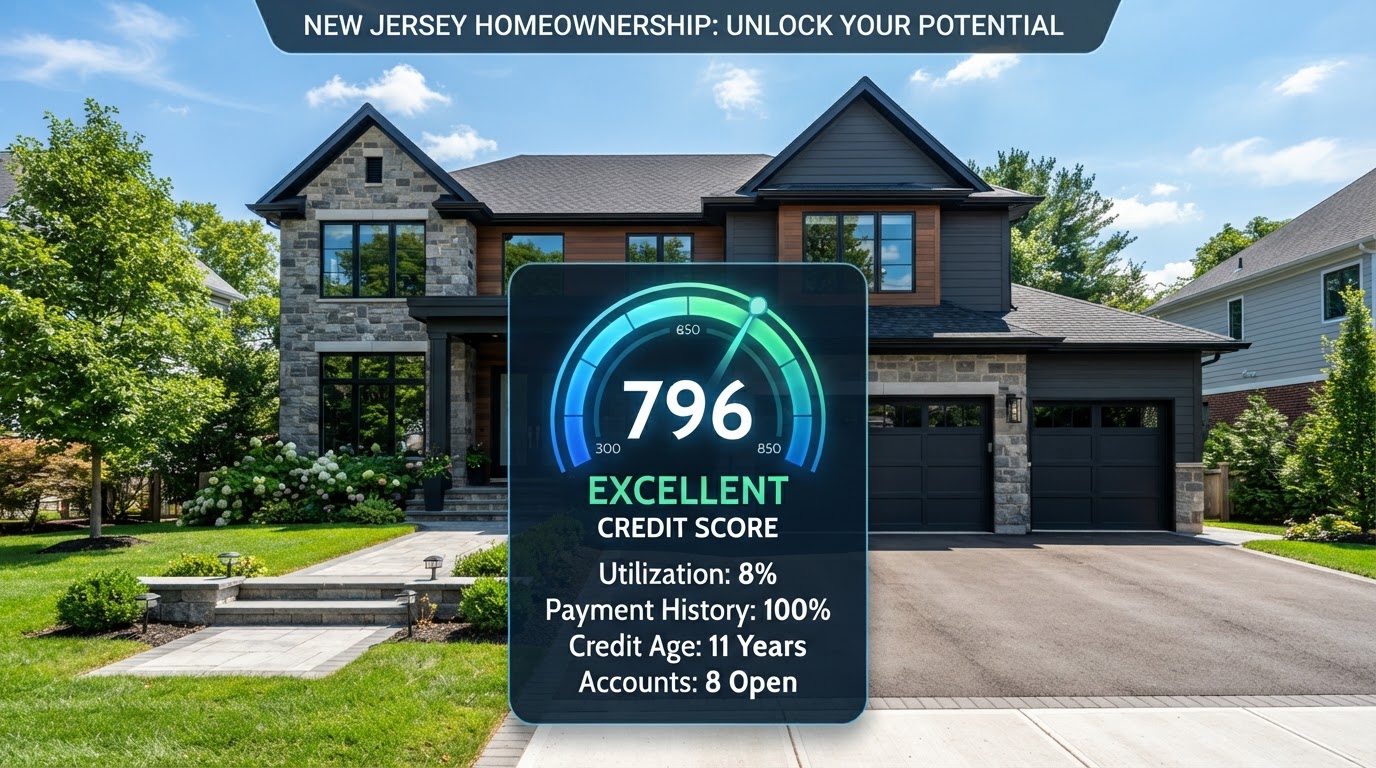
Your credit score is one of the key factors lenders consider when you apply for a mortgage in New Jersey or Florida. It affects whether you qualify, which loan programs are available to you, and the interest rate you receive. Understanding the requirements helps you prepare before you start house hunting — and since the requirements are the same in both states, this guide applies whether you are buying in New Jersey, Florida, or both.
Minimum Credit Scores by Loan Type
The credit score you need depends on the loan program you choose. Here is a breakdown of what lenders look for, with the down payment and key features of each program:
| Loan Type | Min. Credit Score | Down Payment | Key Feature |
|---|---|---|---|
| Conventional | 620 | As low as 3% | PMI removable at 20% equity |
| FHA | 580 (or 500) | 3.5% (or 10% at 500) | Flexible credit guidelines |
| VA | 580 (lender-set) | 0% | No PMI for eligible veterans |
| USDA | 640 | 0% | Eligible rural areas only |
These are general guidelines. Individual lenders may set their own minimums above these thresholds. A higher credit score generally qualifies you for better interest rates and lower costs. This information is educational and does not constitute lending advice.
How Your Credit Score Affects Your Rate
Even a small difference in your credit score can affect your interest rate. A lower rate means a lower monthly payment and less interest paid over the life of the loan. Here is how your score range typically maps to rate tiers on a conventional loan:
| Credit Score Range | Rate Impact | Monthly Payment on $500K Loan |
|---|---|---|
| 740+ | Best rates | Lowest available |
| 680–739 | Slightly higher | +$40–$75/mo vs. 740+ |
| 620–679 | Higher | +$75–$150/mo vs. 740+ |
| Below 620 | FHA likely needed | FHA rates apply |
On a $500,000 New Jersey home, improving your score from 660 to 740 can lower your rate by 0.25% to 0.5%, saving $75 to $150 per month and thousands over the life of the loan. Over 30 years, the savings can be significant.
What If My Score Is Below the Minimum?
If your score is below the minimum for conventional loans, FHA loans offer more flexible credit requirements and allow scores as low as 580 with 3.5% down. Some lenders also offer specialized programs for buyers working to improve their credit. A pre-approval consultation with a lender can clarify your options.
State Assistance Programs for Lower Credit Scores
Both New Jersey and Florida offer down payment assistance programs that work with buyers who have less-than-perfect credit:
| Program | State | Assistance |
|---|---|---|
| NJHMFA | New Jersey | Down payment & closing cost grants/forgivable loans |
| Hometown Heroes | Florida | Up to $35,000 forgivable second mortgage for essential workers |
| Florida Assist | Florida | Down payment help for income-qualified buyers |
How to Improve Your Score Before Buying
- Pay all bills on time, every time — payment history is 35% of your score
- Reduce credit card balances to below 30% of your limits
- Avoid opening new credit accounts or taking on new debt
- Check your credit report for errors and dispute inaccuracies
- Keep old credit accounts open to maintain credit history length
- Ask your lender about a rapid rescore if you recently paid down debt
Related Articles
How Much Down Payment Do You Need to Buy in New Jersey?
What Costs Do Buyers Pay at Closing in New Jersey?
How to Get Pre-Approved for a Mortgage in New Jersey
New Jersey First-Time Home Buyer Programs and Grants
FHA, VA & USDA Home Loans in NJ and FL: A Buyer's Guide
Christian Tibok
New Jersey REALTOR with Fathom Realty NJ LLC. Christian connects buyers with lenders who fit their credit profile. Learn more about Christian.