Real Buying Power Starts With Pre-Approval
Understand your budget, explore loan options, and position yourself as a strong buyer in New Jersey or Florida.
Why Does Financing Confidence Matter Before You Search?
In a competitive market, waiting to figure out your financing can cost you the home. Being pre-approved gives you clarity and leverage from the moment you start your search.
Speed to Offer
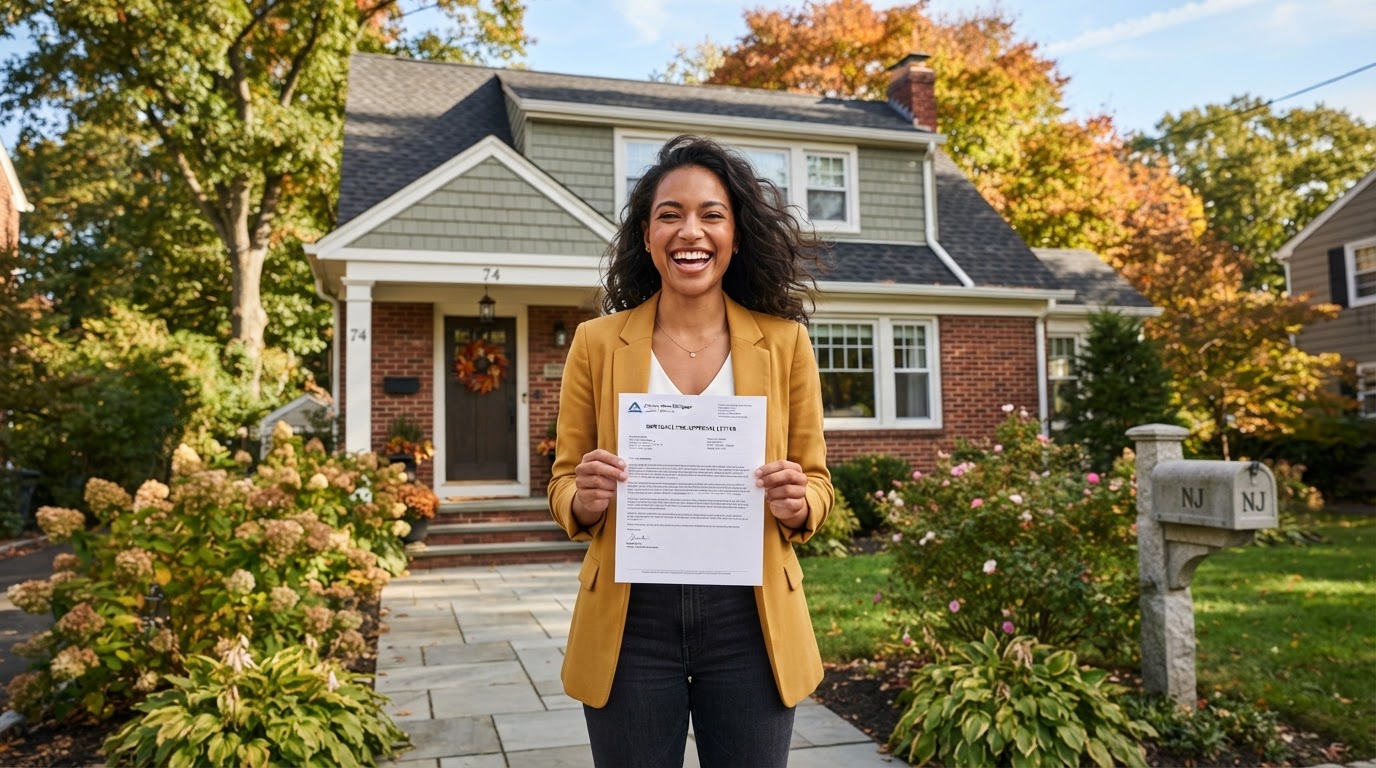
When you find the right home, you need to act fast. A pre-approval letter proves to sellers that you are ready to move forward immediately without financing delays.
Stronger Negotiation
Sellers prefer certainty. A fully pre-approved buyer is often chosen over a buyer with a slightly higher offer who hasn't secured their financing yet.
Payment Planning
Know exactly what your monthly payments will be, understand your interest rate options, and shop for homes that comfortably fit your actual lifestyle budget.
What Is the Difference Between Pre-Qualification and Pre-Approval?
Many buyers confuse these two steps, but sellers definitely know the difference. One is a guess. The other is what wins offers.
Pre-Qualification
A basic overview based on unverified information you provide. It gives you an estimate of what you might borrow, but carries little weight with sellers in a competitive market.
Pre-Approval (What You Need)
A lender has verified your income, assets, and credit. You receive a formal letter stating exactly how much they are willing to lend you. This is what wins offers in New Jersey or Florida.
Documents You'll Need:
- W-2 statements (past 2 years)
- Pay stubs (most recent 30 days)
- Bank statements (past 2 months)
- Tax returns (past 2 years)
- Proof of down payment funds
- Valid ID and Social Security Number
Why Does Getting Pre-Approved First Make You a Stronger Buyer?
"One of the biggest mistakes I see buyers make is falling in love with a home before they understand their financing. The heartbreak of losing a home because of a delayed pre-approval is entirely avoidable."
"My role isn't just to show you houses. It's to help you build a winning strategy. We'll connect you with trusted local lenders who understand the New Jersey and Florida market and can get you positioned to win."
Frequently Asked Questions About Mortgage Pre-Approval in NJ & FL
Smart answers about the pre-approval process.
Does getting pre-approved hurt my credit score?
How long does a mortgage pre-approval last?
Can you recommend a trusted local lender in New Jersey or Florida?
What if I have credit challenges or a low down payment?
Should I get pre-approved before we meet to search for homes?
Related Articles for Buyers
FHA, VA & USDA Home Loans in NJ & FL
Eligibility, down payment, and credit requirements for government-backed loan programs in both states.
Should You Buy Now or Wait?
How to weigh interest rates, inventory, and your personal timeline when deciding the right time to buy.
Mortgage & Financing Guide
Compare conventional, FHA, VA, USDA, jumbo, and DSCR loans and understand your full financing options in NJ & FL.
Free Buyer Guides
Step-by-step buyer resources, checklists, and local market insights for every type of buyer in NJ & FL.
Making a Competitive Offer in NJ or FL
Pre-approval, earnest money, escalation clauses, and appraisal gaps — how to win in a competitive market.
Earnest Money Deposit in NJ or FL
How much to deposit, when it is due, who holds it, and when it is refundable.
Home Inspection for Buyers in NJ or FL
Cost, contingency deadlines, specialty tests, and how to respond when the report comes back.
Low Appraisal: Buyer Options
Renegotiate, challenge, cover the gap, or walk away — your four options when the appraisal falls short.
Buying With Gift Funds or Gift of Equity
Family help for your down payment: gift letter rules, gift of equity from a relative seller, tax limits, and lender verification.
Title Insurance & Property Survey Explained
Owner's vs. lender's policies, the title search, common defects, survey costs, and what to check before you close in NJ or FL.
Private Mortgage Insurance (PMI): Avoid & Remove It
What PMI costs, when it cancels automatically, and how to remove it early so you stop paying it sooner in NJ or FL.
Rent vs. Buy in NJ or FL: Which Is Smarter Now?
Compare NJ's high property taxes and rents against FL's no income tax and carrying costs to decide if buying makes sense for you.
Homeowners Insurance for Buyers in NJ or FL
Lender-required coverage, FL's separate wind and flood policies, hurricane deductibles, and Citizens Insurance explained.
Ready to Build Your Buying Strategy?
Let's discuss your goals, review your financing options, and create a clear path to homeownership in New Jersey or Florida.