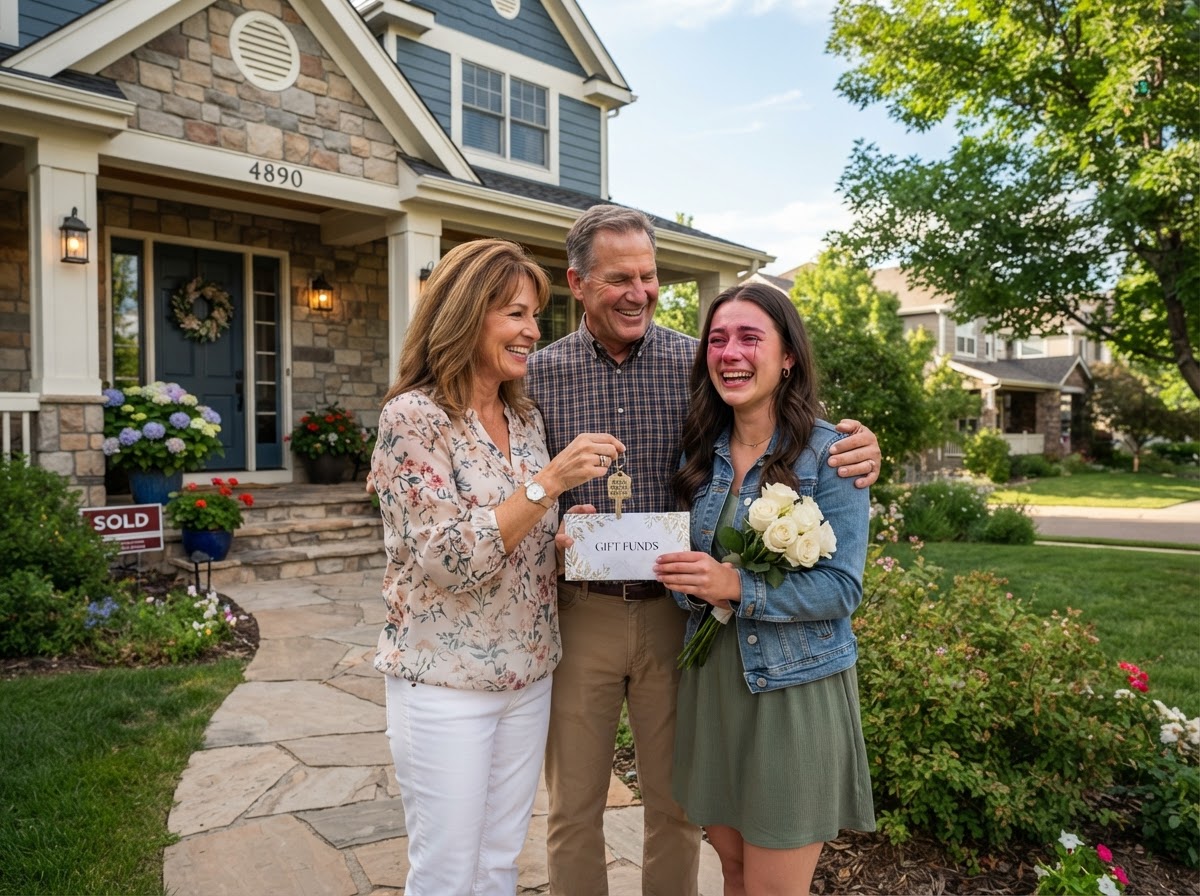
Family assistance is one of the most common ways buyers bridge the gap between savings and a down payment. The good news is that every major loan program allows it — but lenders need documentation to prove the money is a genuine gift, not a disguised loan. Get the details right and the process is smooth; cut corners and you can delay or derail your closing.
What Counts as Gift Funds
Gift funds are money given to you by an acceptable donor to help with your down payment, closing costs, or reserves. The defining feature is that there is no expectation of repayment. If the money is a loan — even an informal one — the lender must count it as debt, which can hurt your qualification.
Acceptable donors typically include:
- Parents or grandparents
- Spouse or domestic partner
- Fiancé or engaged partner
- Siblings, aunts, uncles, or cousins
- Close friends with a documented, clearly defined relationship (conventional loans)
The Gift Letter: What It Must Include
Every lender requires a gift letter signed by the donor. Your loan officer will provide a standard form, but it must include:
- The donor's name, address, and phone number
- Your name and your relationship to the donor
- The exact dollar amount of the gift
- The date the funds were or will be transferred
- The property address being purchased
- A clear statement that no repayment is expected or required
The lender will also verify the funds — typically by reviewing the donor's bank statement showing the money leaving and your statement showing it arriving. Large cash deposits that cannot be traced will be questioned, so make sure the transfer is clean and documented.
Gift of Equity: Buying From a Family Member
A gift of equity is a special case that applies when you buy a home from a family member for less than its appraised value. The difference between the sale price and the appraised value is treated as your down payment.
For example: a parent sells you a home appraised at $400,000 for $320,000. The $80,000 difference is the gift of equity. You bring little or no cash to closing, and that equity satisfies the down payment requirement. This is common in life-transition situations — helping a child buy their first home, or transferring a family property. See our guide on selling a house to a family member for the seller's perspective.
- Conventional: A gift of equity from a family member can fund the entire down payment.
- FHA: The same applies — the equity counts as your invested funds.
- Mortgage insurance: A large gift of equity can push your loan-to-value below 80%, eliminating mortgage insurance on a conventional loan.
Tax Considerations for the Donor
Gift tax is the donor's responsibility, not the buyer's. For 2026, the annual gift exclusion lets a donor give up to $19,000 per recipient without filing a gift tax return. A married couple can jointly give up to $38,000 to one person. Gifts above that amount are generally still tax-free because they count against the donor's lifetime exemption (over $13 million), but the donor may need to file a gift tax return. A gift of equity follows the same rules — the equity amount is treated as a gift for tax purposes. Always consult a tax professional for your specific situation.
Using Gift Funds for Closing Costs and Reserves
Gift funds are not limited to the down payment. They can also cover closing costs and the cash reserves some lenders require. FHA and conventional loans both allow this. Just make sure the gift letter and documentation cover the full amount you intend to use. If you are unsure what your closing costs will be, review our NJ buyer closing costs and FL buyer closing costs guides.
Common Mistakes to Avoid
- Untraceable deposits: Cash deposited into your account without a paper trail will be flagged. Always transfer via check or wire from the donor's account.
- Verbal promises: A loan dressed up as a gift violates loan requirements. If repayment is expected, it must be disclosed and counted as debt.
- Wrong donor: Gifts from unrelated parties who are not close friends may not be acceptable on some loan types. Confirm with your lender before accepting the money.
- Timing: Transfer the funds after your loan officer tells you to, and keep all documentation. Early or undocumented transfers create underwriting delays.
Next Steps for NJ and FL Buyers
If family help is part of your plan, start with a pre-approval so your lender can tell you exactly what documentation they need. Review your down payment options and no-money-down programs to see how gift funds fit alongside other assistance. For first-time buyers, explore NJ programs and FL programs that pair well with gift funds.
Ready to put a plan together? Schedule a conversation with Christian, or browse our full buyer guides and financing resources.
Christian Tibok
REALTOR serving homeowners across New Jersey and Florida. Christian helps buyers navigate gift funds, family sales, and financing so the paperwork never derails a closing. Learn more about Christian.