
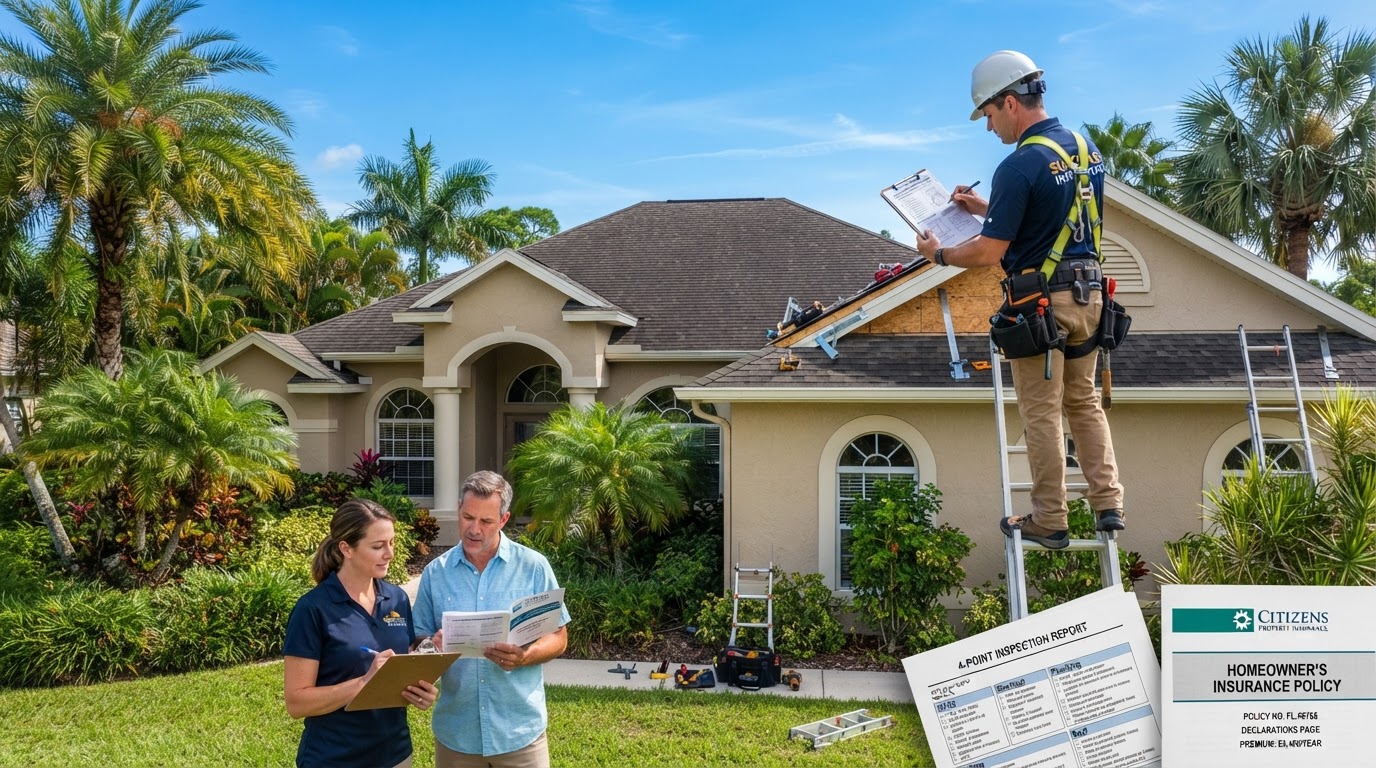
Florida's insurance market is unlike any other. Premiums are high, underwriting is strict, and a home's insurability can make or break a sale. For sellers, understanding how wind mitigation, 4-point inspections, and insurance requirements affect buyers is essential. A home that is easy and affordable to insure attracts more buyers and stronger offers. Here is what Florida sellers need to know.
Why Insurance Is Central to Every Florida Sale
In Florida, a buyer's lender requires a homeowners insurance policy before closing, and flood insurance if the home is in a flood zone. The cost and availability of that insurance directly affects the buyer's monthly payment and purchasing power. If a home is expensive or difficult to insure, buyers may offer less, struggle to qualify, or walk away entirely.
This means that as a seller, your home's insurability is a selling point or a hurdle. The more you can do to make your home affordable to insure, the smoother and more profitable your sale will be. For the broader Florida selling picture, see our guide to selling a house as-is in Florida.
What Is Wind Mitigation?
Wind mitigation is an inspection that documents the wind-resistant features of your home. Florida insurers offer premium credits for features that reduce the risk of wind damage, because those features lower the likelihood of a claim.
Common wind mitigation features include:
- Roof shape: Hip roofs generally receive better credits than gable roofs.
- Roof-to-wall attachments: Hurricane straps, clips, or anchors that secure the roof to the walls.
- Storm shutters or impact-rated openings: Protection for windows and doors against wind-borne debris.
- Roof age and covering: Newer roofs with approved materials receive better ratings.
- Secondary water resistance: A barrier that prevents water intrusion if the roof covering is damaged.
A favorable wind mitigation report can reduce a buyer's premium by hundreds or even thousands of dollars per year. Providing a current report to buyers is a powerful marketing tool.
The 4-Point Inspection
A 4-point inspection evaluates four critical systems: roof, electrical, plumbing, and HVAC. Most Florida insurers require a 4-point inspection for homes older than 20 years before issuing a policy. The insurer wants to confirm that these systems are in good condition and not likely to cause a claim.
If any system is at or near the end of its useful life, the insurer may decline coverage or require a replacement before binding a policy. This can delay or derail a sale. If your home is older, consider having the key systems evaluated before listing so you can address issues proactively or price the home to reflect needed updates.
Citizens Insurance and the Private Market
Citizens Property Insurance Corporation is Florida's state-backed insurer of last resort. When a home cannot be insured in the private market, Citizens provides coverage, often at higher premiums and with stricter terms.
If your home can only be insured through Citizens, buyers face higher costs and more uncertainty. Reducing the need for Citizens by maintaining wind mitigation features, updating aging systems, and keeping the roof in good condition makes your home more attractive to private insurers and, by extension, to buyers.
How Insurance Affects Your Sale Price
Buyers factor insurance costs into their monthly housing budget. If your home carries a $4,000 annual premium and a comparable home carries $2,500, the buyer of your home has less purchasing power. This can translate into a lower offer.
Conversely, a home with strong wind mitigation credits, a newer roof, and updated systems is cheaper to insure, which supports a stronger asking price. A home value estimate that accounts for insurance costs helps you price realistically.
Steps to Make Your Florida Home More Insurable
- Get a current wind mitigation inspection and share the report with buyers.
- If your roof is near the end of its life, consider replacing it before listing. A new roof is one of the most powerful insurability and value improvements.
- Update aging electrical, plumbing, and HVAC systems so the home passes a 4-point inspection.
- Install or document storm shutters, impact windows, or other opening protection.
- If you are in a flood zone, provide a current elevation certificate. See our guide to selling in a flood zone.
- Gather all insurance documentation so buyers can get accurate quotes quickly.
Selling As-Is When Insurance Is a Challenge
If your home has an older roof, aging systems, or other insurability challenges and you do not want to invest in updates, an as-is sale is a valid option. A cash buyer or investor may accept the property without requiring immediate insurance-driven repairs, though the offer will reflect the condition. Compare your as-is and traditional-sale options with our options comparison to see which nets you more.
Insurance Readiness Sells Homes
In Florida's market, the homes that sell fastest and for the best prices are the ones that are easy and affordable to insure. By understanding wind mitigation, 4-point inspections, and the insurance landscape, you can position your home to attract confident, financed buyers. Start with a home value estimate or schedule a conversation with Christian to plan your sale.
Related Reading for Florida Sellers
For more, read about selling in a flood zone, seller closing costs in Florida, or Florida's homestead exemption.

Christian Tibok
REALTOR serving homeowners across New Jersey and Florida. Christian helps Florida sellers navigate insurance requirements, wind mitigation, and as-is selling options. Learn more about Christian.