
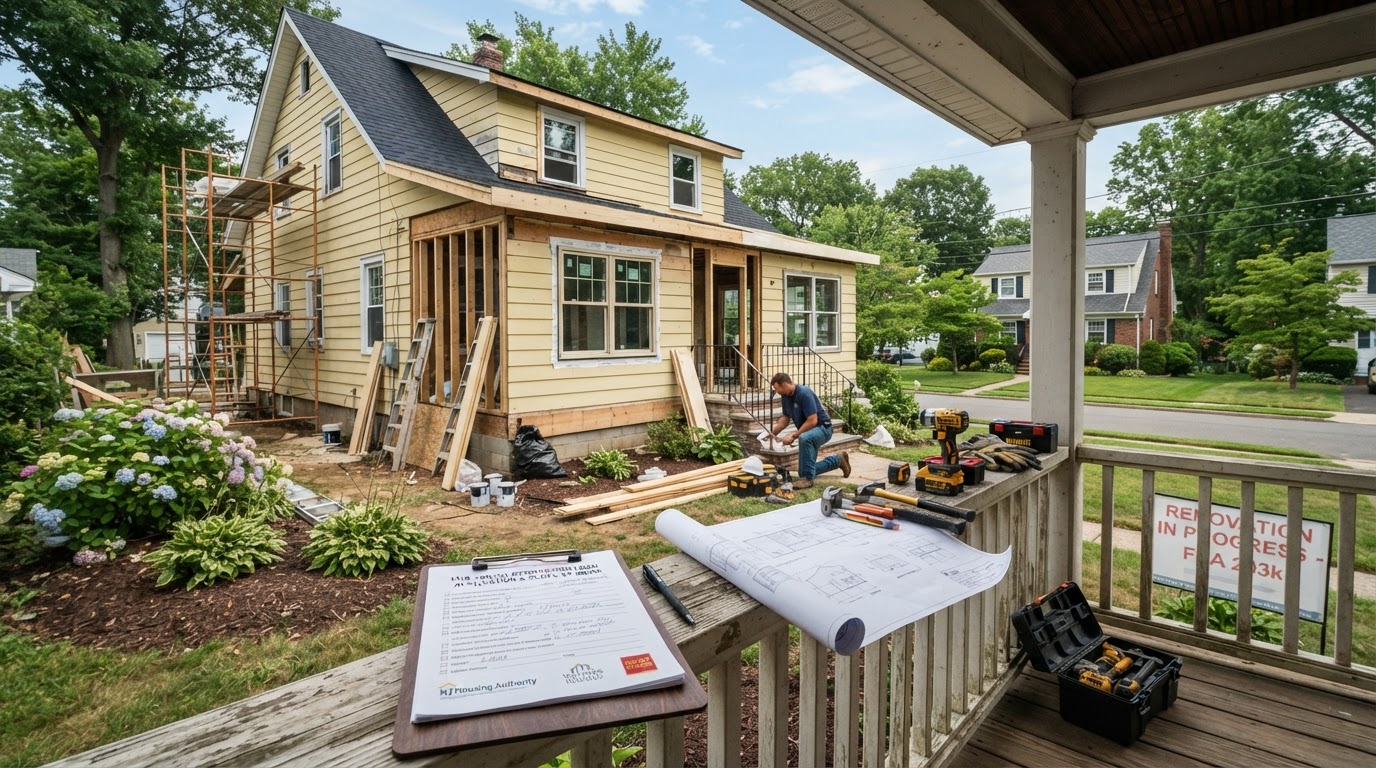
In both New Jersey and Florida, fixer-uppers are often the most affordable homes on the market. The challenge is paying for the repairs. The FHA 203k renovation loan solves that problem by letting you finance the purchase and the renovation in a single mortgage — one closing, one monthly payment. For buyers who want to build equity and customize a home, it is one of the most powerful tools available.
What Is an FHA 203k Loan?
The FHA 203k is a government-backed renovation loan. Instead of buying a home and then taking out a separate loan or using savings for repairs, you borrow enough to cover both the purchase price and the renovation cost in one mortgage.
There are two versions:
- Standard 203k: For major renovations including structural work like foundation repair, room additions, and reconstruction. Requires a 203k consultant and has a $5,000 minimum renovation cost.
- Limited 203k: For non-structural work up to $35,000 — things like roofing, plumbing, HVAC, kitchens, baths, flooring, and energy upgrades. Simpler process, no consultant required.
Who Qualifies for a 203k Loan in NJ or FL?
- Credit score: Minimum 580 at most lenders (some require 620). The same accessible threshold as a standard FHA loan. See our guide to buying with bad credit.
- Down payment: 3.5% of the combined purchase price plus renovation cost.
- Property: Must be a 1–4 unit residential property. You must occupy it as your primary residence.
- DTI: Generally up to 43–50%, same as standard FHA.
Because the 203k is an FHA product, it shares the same FHA loan benefits — low down payment, flexible credit, and competitive rates.
What Repairs Are Eligible?
The 203k is flexible, but it is not unlimited. Eligible work includes:
- Roof replacement, gutters, and exterior repairs.
- Plumbing, electrical, and HVAC updates.
- Kitchen and bathroom remodels.
- Flooring, painting, and finish work.
- Energy-efficiency upgrades like insulation and windows.
- Mold and water damage remediation (with source repair).
- Foundation repair and structural work (Standard 203k only).
Luxury items like swimming pools, outdoor kitchens, and purely cosmetic upgrades are generally not eligible. The work must improve the home's safety, function, or value.
How the Renovation Process Works
- 1. Get bids: Obtain contractor bids for the work you want done. For a Standard 203k, a 203k consultant helps create a work write-up and cost estimate.
- 2. Close on the loan: You close once, financing the purchase and renovation together.
- 3. Renovation funds are escrowed: The renovation money is held in an escrow account and released in draws as work is completed and inspected.
- 4. Work is completed: Your contractor does the work; the consultant or lender inspects each stage before releasing the next draw.
- 5. Final inspection: A final inspection and any required warranties close out the renovation portion of the loan.
Most 203k renovations are completed within 6 months of closing. The process is more involved than a standard purchase, but the result is a home renovated to your specifications.
203k vs. Move-In Ready: Which Is Right for You?
- Choose 203k if: You want to build equity, you are comfortable managing a renovation, and you want to customize the home. It is often the most affordable path in competitive NJ and FL markets.
- Choose move-in ready if: You want simplicity and speed, you do not want to manage contractors, or you need to move in immediately.
If you already own a home and need to fund major repairs, the 203k can also be used as a refinance — a smart option for NJ and FL homeowners facing foundation problems or mold and water damage who would rather renovate than sell.
Is a Fixer-Upper Right for You?
The 203k is not the only way to buy a fixer-upper, but it is one of the most accessible. If you are weighing a fixer-upper against a move-in ready home, start with pre-approval to see what you qualify for, use our mortgage calculator to model payments, and schedule a conversation with Christian to map out whether a 203k fits your goals.
Related Reading for NJ and FL Buyers
For more, read about FHA, VA & USDA loans, how much house you can afford, or down payment requirements.

Christian Tibok
REALTOR serving homeowners across New Jersey and Florida. Christian helps buyers evaluate fixer-uppers and connect with 203k lenders and contractors. Learn more about Christian.